Building physical wealth requires a thoughtful approach, not just to which assets you acquire but also to their physical form. I have seen many people focus solely on the type of asset, like gold or silver, but overlook the crucial aspect of sizing options. The physical size and denomination of your tangible assets can significantly impact their liquidity, storage, and even their long-term value. It is more than just choosing what to buy, it is about choosing how to hold it.
Understanding the different sizing options for physical wealth is a fundamental step for any serious investor or collector. From small, easily traded pieces to larger, more substantial holdings, each size category offers distinct advantages and disadvantages. I want to explore these various considerations so you can make informed decisions that align with your personal financial strategy and goals.
My goal here is to give you a clear picture of how sizing affects your physical wealth. We will look at everything from small bars to large real estate holdings. This will help you manage your investments better.
Understanding Different Forms of Physical Wealth
When I talk about physical wealth, I am referring to tangible assets that hold intrinsic value outside of the financial system. These assets are things you can touch, see, and store. They include precious metals like gold and silver, but they also extend to other valuable items like rare art, high-value collectibles, and even certain types of real estate. The beauty of physical wealth is its enduring nature and its ability to act as a hedge against economic uncertainties.
The choice of form is often the first decision. Some people prefer the universal recognition and fungibility of precious metals. Others gravitate towards unique items that may appreciate over time due to rarity or cultural significance. It is important to consider both the asset class and its physical representation when building a robust portfolio of tangible holdings. This helps ensure diversification.
Precious Metals as a Foundation
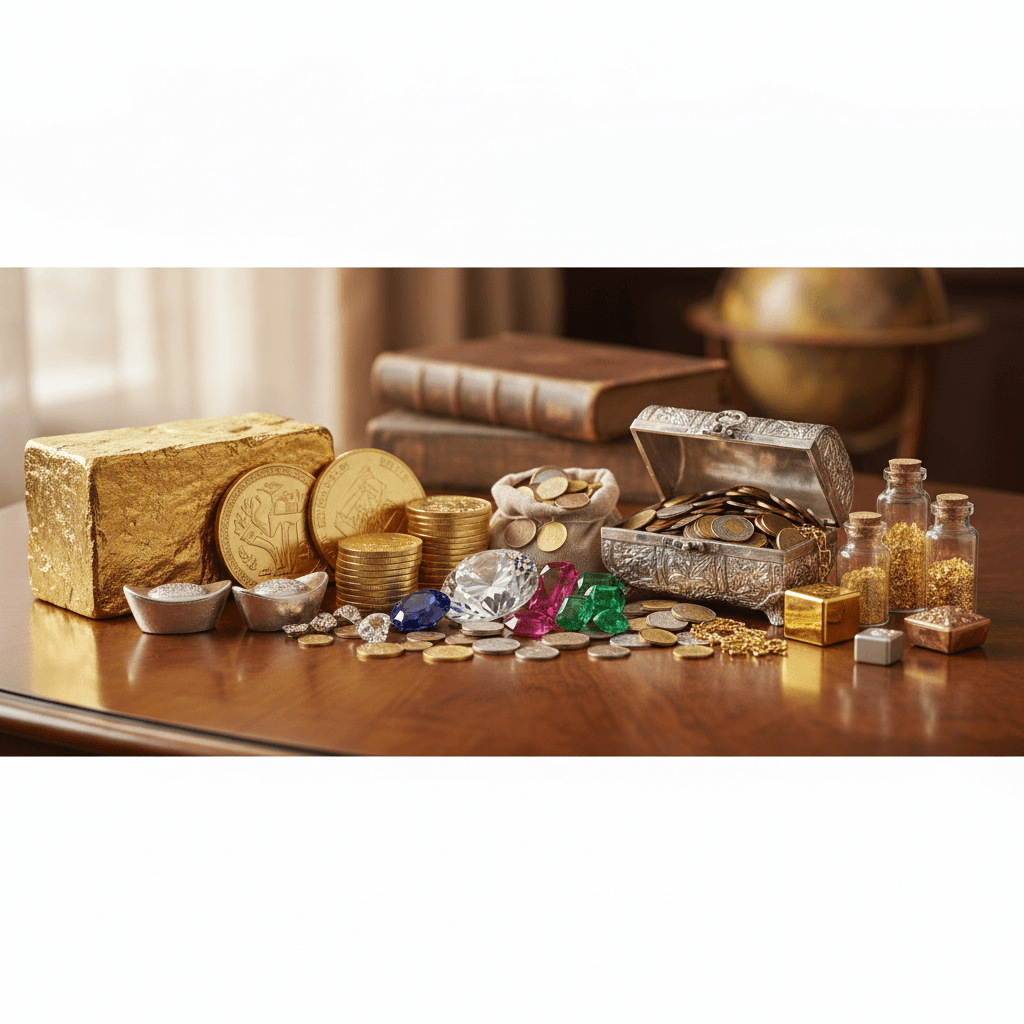
For many, precious metals are the bedrock of physical wealth. Gold and silver in particular are widely accepted as stores of value across the globe. These metals come in a variety of sizes and forms, including coins, bars, and rounds. The purity and weight are usually stamped directly onto the item, providing immediate verification of its content.
I have learned that the appeal of precious metals lies in their liquidity and their role as a safe haven during economic turmoil. They are also relatively easy to store in secure locations. The sizing options for gold and silver are quite diverse, ranging from fractional weights suitable for smaller budgets to large industrial-sized bars for significant investments. This flexibility allows investors to tailor their holdings to their specific needs and financial capacity.
Real Estate and Tangible Assets
Beyond precious metals, physical wealth also encompasses assets like real estate. While often considered an investment, real estate represents tangible property that can provide income or serve as a personal residence. Its size is inherently large, making it a less liquid but potentially highly appreciating asset.
Other tangible assets include fine art, antique furniture, rare stamps, and vintage automobiles. These items often require specialized knowledge for valuation and care. Their size can vary greatly. A rare coin is small and easily stored, while a classic car requires substantial space and maintenance. The choice among these forms depends on your expertise and storage capabilities.
Small Denominations for Accessibility and Liquidity
Small denominations of physical wealth are often overlooked by new investors, but they offer distinct advantages. These smaller units provide excellent flexibility. They allow for incremental investments and make it easier to liquidate a portion of your holdings without having to sell a much larger asset. This increased accessibility is beneficial for those who are just starting to build their physical wealth or who want to maintain a high degree of control over their assets.
I find that having a mix of sizes is smart. You get the stability of larger pieces with the ease of smaller ones. This strategy can help you respond to changing market conditions or personal financial needs quickly. It creates a balanced and adaptable portfolio.
Fractional Gold and Silver
Fractional pieces of gold and silver are excellent for accessibility. These can be gold coins in 1/10th or 1/4th ounce sizes or small silver rounds. They allow individuals to enter the precious metals market with a smaller initial investment. They also provide greater flexibility for future transactions.
I often suggest fractional pieces for those looking to gift physical wealth or for emergency preparations. Their smaller value makes them more practical for bartering or smaller transactions if traditional currency systems face disruption. It is like having cash on hand, but in a more stable, physical form.
Collectibles and Their Value
Collectibles, such as rare coins, stamps, or even trading cards, can also represent small-sized physical wealth. The value here is not just in the material, but in its rarity, historical significance, or artistic merit. A single rare coin can be worth a substantial amount, yet it takes up very little physical space.
For example, a high-grade ancient coin or a rare mint error coin holds significant value and can be easily stored in a small safe. These items are distinct from bullion because their price is less tied to the spot price of the metal. Instead, their value comes from collector demand and scarcity. This makes them a unique component in a physical wealth strategy.
Medium to Large Sizing Options for Physical Wealth Accumulation
When an investor moves beyond initial acquisitions, they often start looking at medium to large sizing options. These choices are typically for accumulating significant physical wealth over time. They tend to offer better value per unit of metal, so you pay less premium compared to smaller, fractional pieces. This makes them cost-effective for larger investments.
I have observed that these larger denominations are favored by long-term investors. They are not as concerned with immediate liquidity for small transactions. They prioritize maximizing their holdings. This scale of investment usually requires more robust storage solutions, but the benefits in terms of cost efficiency can be substantial.
Standard Bullion Products
Standard bullion products are a core component of many physical wealth portfolios. These include common sizes like 1 ounce gold coins, 10 ounce silver bars, or even larger pieces. These items are widely recognized and highly liquid within the global bullion market. Their standardized weights and purities simplify buying and selling processes.
For example, a 1 kilo gold bar is a popular choice among serious bullion buyers. This size offers an excellent balance between a substantial investment and manageable liquidity. It represents a significant store of wealth in a single unit. These larger bars generally have lower premiums over spot price when compared to smaller bars or coins, making them efficient for wealth accumulation. We see similar benefits with 100-ounce silver bars or even 1,000-ounce silver bars, depending on the scale of investment.
Other Significant Tangible Assets
Beyond standard bullion, other tangible assets also come in significant sizes. These might include larger pieces of investment-grade diamonds, substantial collections of fine art, or even entire tracts of land. These assets often represent considerable value and require specialized knowledge for both acquisition and appraisal. Their size dictates unique storage and management considerations.
For example, a significant art piece demands climate-controlled storage and specialized insurance. Land or property investments involve legal complexities and ongoing maintenance. While these assets offer potential for substantial appreciation, their larger size and specialized nature mean they are less liquid than precious metals. Investors often acquire these assets for their specific utility or long-term growth potential. They are not for quick access to funds.
Practical Considerations for Storing and Transporting Physical Wealth
Once you decide on your sizing options for physical wealth, the next crucial step is considering how to store and, if necessary, transport these assets safely. I understand that the physical nature of these investments means they are susceptible to theft, damage, or loss. Proper planning in this area is just as important as the acquisition itself. Neglecting storage can undermine all your efforts to build and protect your wealth.
Different sizes of assets will naturally require different storage solutions. A single gold coin can be stored differently than a collection of large silver bars or a valuable painting. We must think about security, accessibility, and environmental conditions when making these choices. This protects your investment for the long haul.
Secure Storage Solutions
For smaller items like coins, fractional bars, or rare collectibles, a home safe can offer a reasonable level of security. However, for larger holdings, a more robust solution is often warranted. Bank safe deposit boxes are a common choice. They provide strong physical security and protection against fire or flood. But they do have limitations, such as restricted access hours and the fact that contents are not federally insured.
For significant bullion holdings, I recommend specialized private vaults or depository services. These facilities offer high-level security, climate control, and often include insurance. They are designed specifically for precious metals and other valuable tangible assets. While there are fees associated with these services, the peace of mind and enhanced security they provide can be well worth the cost.
Insuring Your Tangible Assets
Insurance is a vital component of protecting your physical wealth. Even the most secure storage solutions can have vulnerabilities. Standard homeowner’s insurance policies often have very low limits for precious metals, jewelry, and other high-value collectibles. It is crucial to review your policy and understand its coverage limitations.
I always advise clients to obtain a separate, specialized insurance policy for their tangible assets. This might be a “floater” policy that covers specific items for their appraised value, or a policy from a specialized insurer for bullion and collectibles. Make sure to regularly update your inventory and valuations. This ensures your coverage remains adequate as the value of your assets changes or as you acquire more. This foresight protects your investments from unforeseen events.
Diversifying Your Physical Wealth Portfolio with Various Sizes
Diversification is a well-known principle in financial planning, and it applies equally to physical wealth. Beyond diversifying across different asset classes, it is also wise to diversify your holdings within physical wealth by choosing various sizing options. This strategy enhances both liquidity and resilience. It prepares you for a wider range of economic scenarios and personal needs.
I find that a varied approach allows for flexibility. You can sell small pieces if you need quick cash. You can keep larger pieces for long-term growth. This balance is key to a robust wealth strategy. It gives you options and helps manage risks.
Balancing Small and Large Holdings
A balanced approach often involves holding a mix of small, medium, and large denominations. Small units, like 1/10th ounce gold coins or 1-ounce silver rounds, provide immediate liquidity for minor expenses or bartering. Medium units, such as 1-ounce gold bars or 10-ounce silver bars, are good for mid-sized transactions or selling off moderate amounts of capital.
Large units, like 100-ounce silver bars or kilogram gold bars, are typically held for long-term capital preservation and significant wealth storage. They benefit from lower premiums per unit weight. By having a mix, you avoid being forced to sell a large, high-value asset when you only need a small amount of cash. This can save you money on transaction costs and help preserve your larger investments.
The Role of Different Asset Classes
In addition to varying sizes within precious metals, consider diversifying into other physical asset classes. This might mean allocating a portion of your wealth to rare collectibles, unique art pieces, or even investment-grade gemstones. Each of these classes has its own market dynamics, value drivers, and sizing options.
For example, a rare stamp collection could be considered many small, individual pieces of wealth. A single large antique can be one significant asset. I believe that by spreading your physical wealth across different types of tangible assets and various sizes, you create a more resilient portfolio. This reduces dependence on any single market segment. It also helps mitigate risks associated with specific economic or geopolitical events.
Choosing the Right Sizing Options for Your Financial Goals
Selecting the right sizing options for your physical wealth is a very personal decision. It should align directly with your overall financial goals and risk tolerance. There is no one-size-fits-all answer. What works for one investor might not work for another. I always advise taking the time to assess your individual circumstances before making any purchases.
Consider your investment horizon, your need for liquidity, and your available storage solutions. Do you foresee needing quick access to small amounts of capital, or are you primarily focused on long-term capital preservation? These questions will guide your choices. They help create a strategy that truly fits your life.
Final Thoughts on Sizing Options for Physical Wealth
Choosing the correct sizing options for your physical wealth is a critical element of effective asset management. It is not enough to simply decide what type of physical asset to acquire. You must also consider the practical implications of its physical form and weight. Small denominations offer flexibility and liquidity, making them ideal for smaller transactions or emergency needs. Larger denominations provide greater cost efficiency and are suitable for long-term wealth accumulation. A diversified approach, incorporating a mix of sizes and asset types, typically yields the most robust and adaptable portfolio.
I encourage you to evaluate your personal financial objectives, your storage capabilities, and your potential need for liquidity. This thoughtful consideration will help you select the optimal sizing strategy for your physical wealth. By doing so, you can build a tangible asset portfolio that is secure, efficient, and aligned with your unique financial future. Start planning today to ensure your physical wealth serves your needs both now and for years to come.